
SUBHASH CHANDRA’S PROPOSED BAILOUT: IS IT NOT A SANCTIONED LOOT?
Subhash Chandra's bailout raises a pointed question: if a
prominent promoter like him can walk away from a personal guarantee this easily, what
does the Insolvency and Bankruptcy Code's personal insolvency framework
actually protect? It looks less like resolution and more like sanctioned loot.
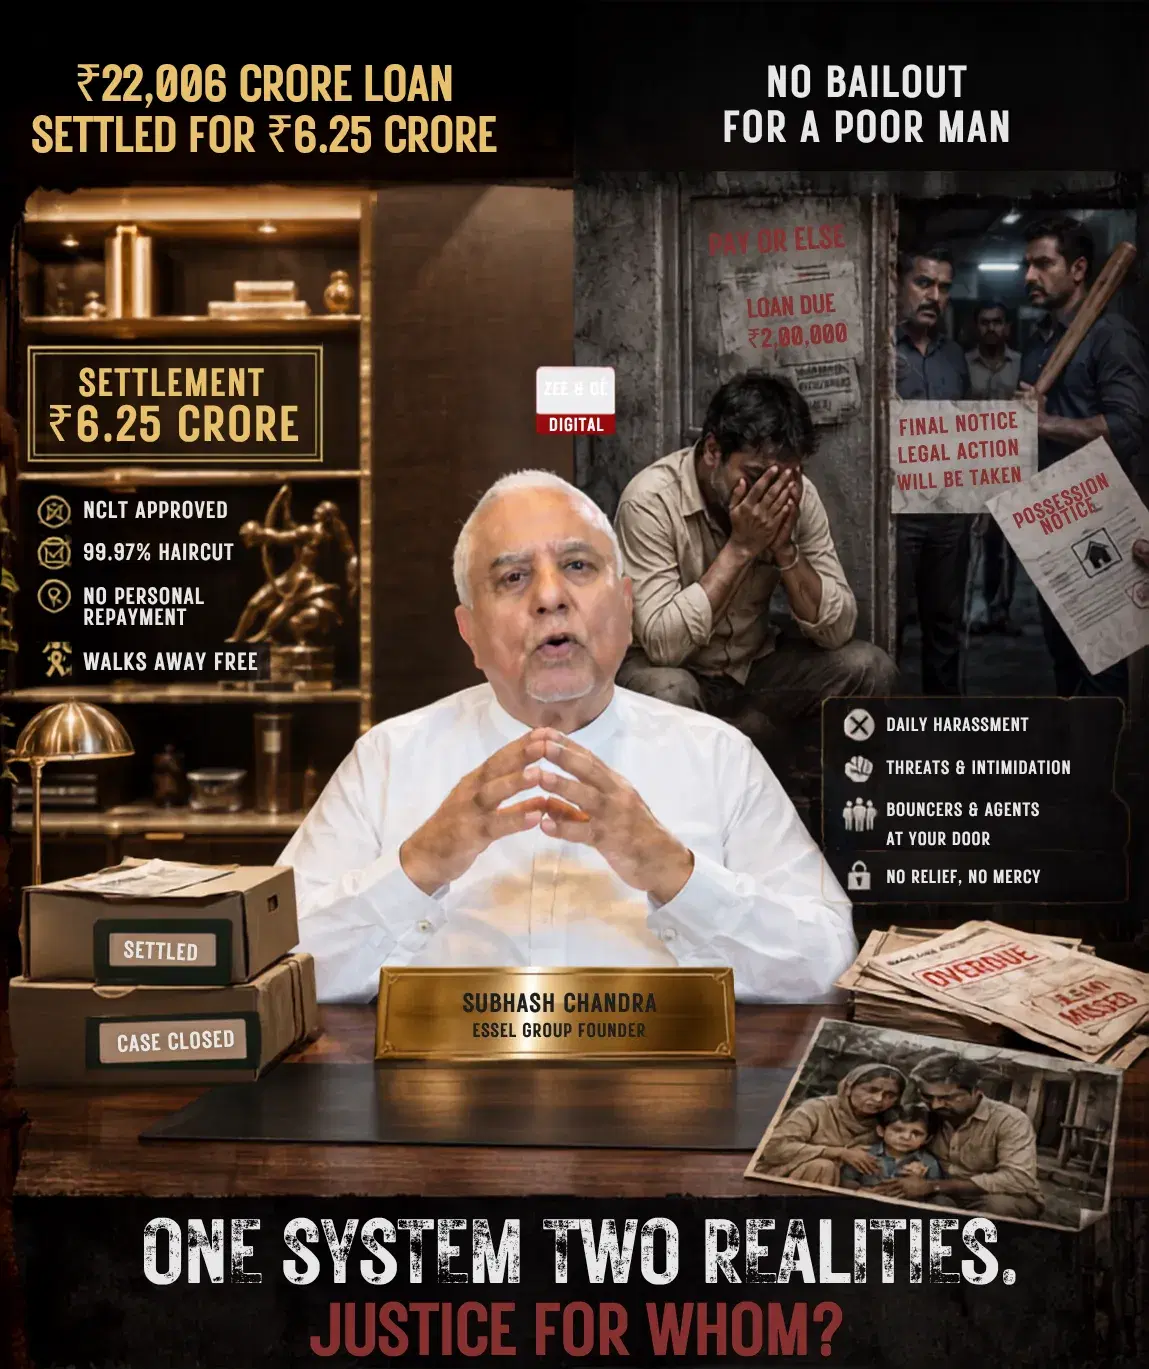
It's almost too absurd to believe. The National Company Law Tribunal
(NCLT) approved a ₹6.25-crore settlement from Essel Group founder Subhash
Chandra against a personal guarantee of ₹22,006.57 crore — debts accrued by
companies linked to the Essel Group.
The math is brutal: financial institutions absorbed a 99.97% haircut,
recovering barely 0.03% of what they were owed. Major lenders, including HDFC
Bank and LIC Housing Finance, fought the plan hard, calling the recovery
trivial and unviable. The episode has set off alarm bells across India's
banking and legal circles, raising a pointed question: if a prominent promoter
can walk away from a personal guarantee this easily, what does the Insolvency
and Bankruptcy Code's personal insolvency framework actually protect? It looks
less like resolution and more like sanctioned loot.
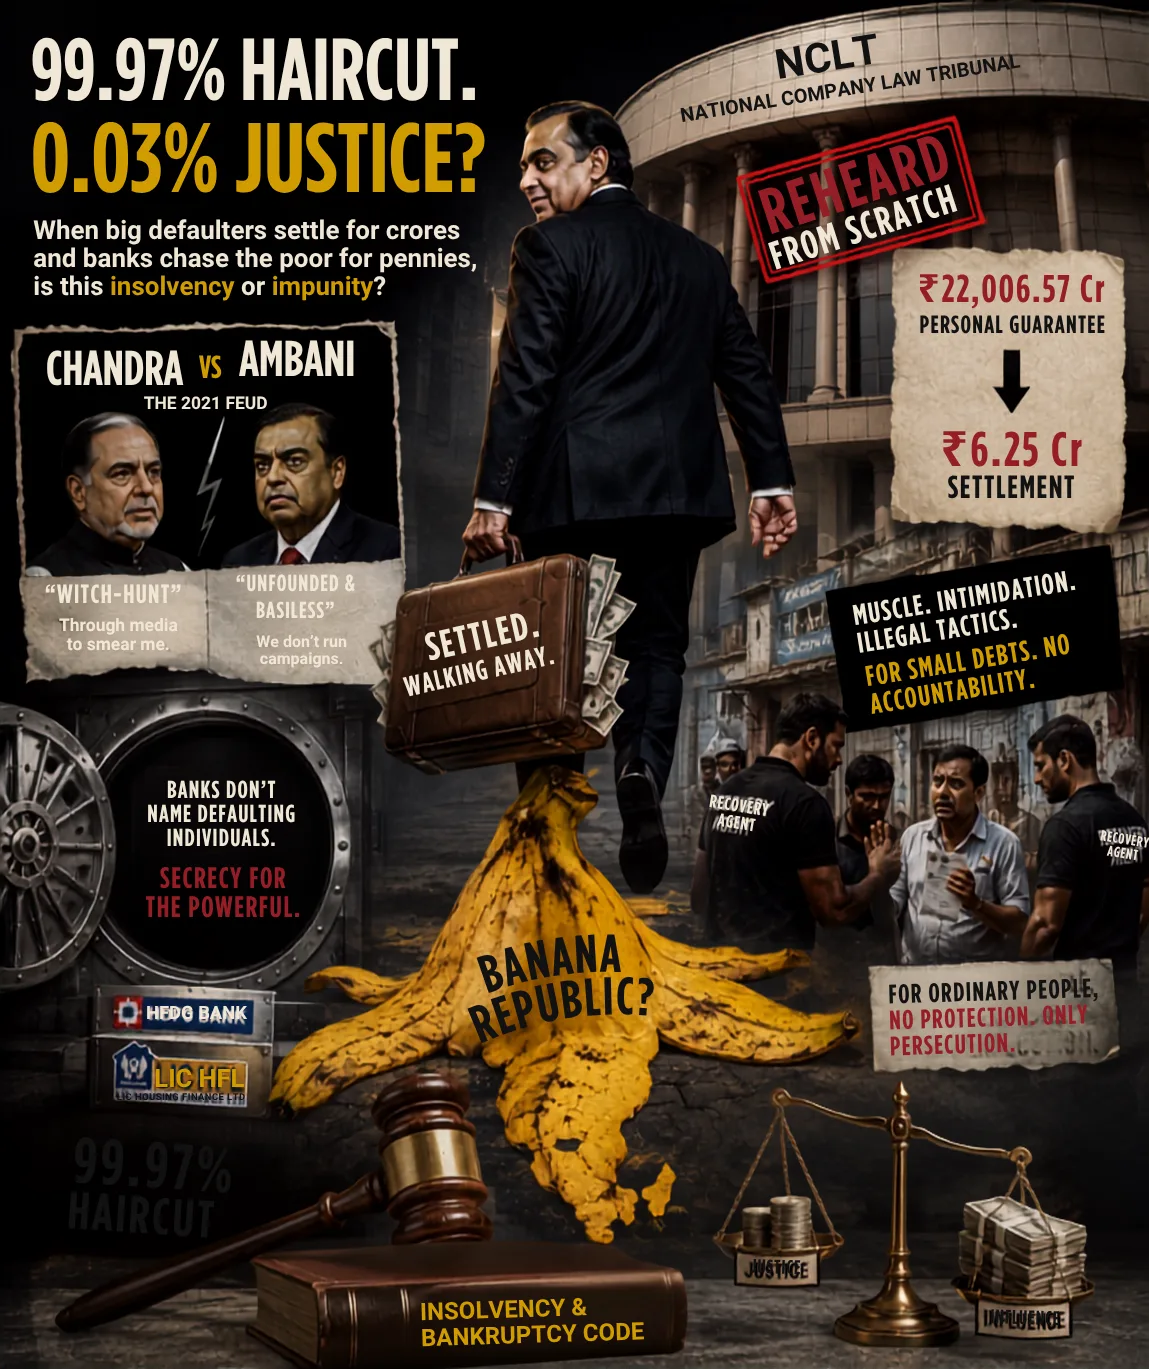
Then came the twist. Chandra — the chief beneficiary of this outcome, and
also the founder of Zee — released an explosive video accusing Reliance
Industries Chairman Mukesh Ambani of orchestrating a "witch-hunt"
through his media outlets to smear him over the case. In doing so, he reopened
a bitter 2021 feud, alleging Reliance had colluded with foreign investor
Invesco to engineer a hostile takeover of Zee Entertainment while the network
was financially exposed.
A few days later, Chandra held an Instagram Q&A — this time notably
silent on Ambani, sticking to explanations of how borrowers were settling with
lenders. But the video had already gone viral, and the damage was done.
Reliance issued a sharp denial, calling the allegations "unfounded and
baseless" and stating flatly that its media outlets have never been used
to target individuals or run corporate campaigns.
Then, in an unprecedented move, a five-member NCLT bench — led by
President Justice (Retd.) Anupinder Singh Grewal — took up the matter suo motu,
stayed the original order, and decided to rehear the case from scratch, citing
a lack of clear consensus among the earlier members.
The bigger story sits underneath all this noise. Banks and NBFCs
publish aggregate NPA figures but never name individual defaulters — a
selective anonymity shielded by banking secrecy laws. Yet these same
institutions, when chasing ordinary borrowers for far smaller sums, routinely
deploy musclemen, bouncers, and unauthorized recovery agents — illegal tactics
that are simply cheaper and faster than the courts.
The real scandal isn't a missing law. It's an execution gap: elaborate,
well-lawyered machinery for corporate promoters, and a threadbare, poorly
enforced system for everyone else.
Are we a banana republic?